| |
|
|
 Home /
MOOWR
-
-
-
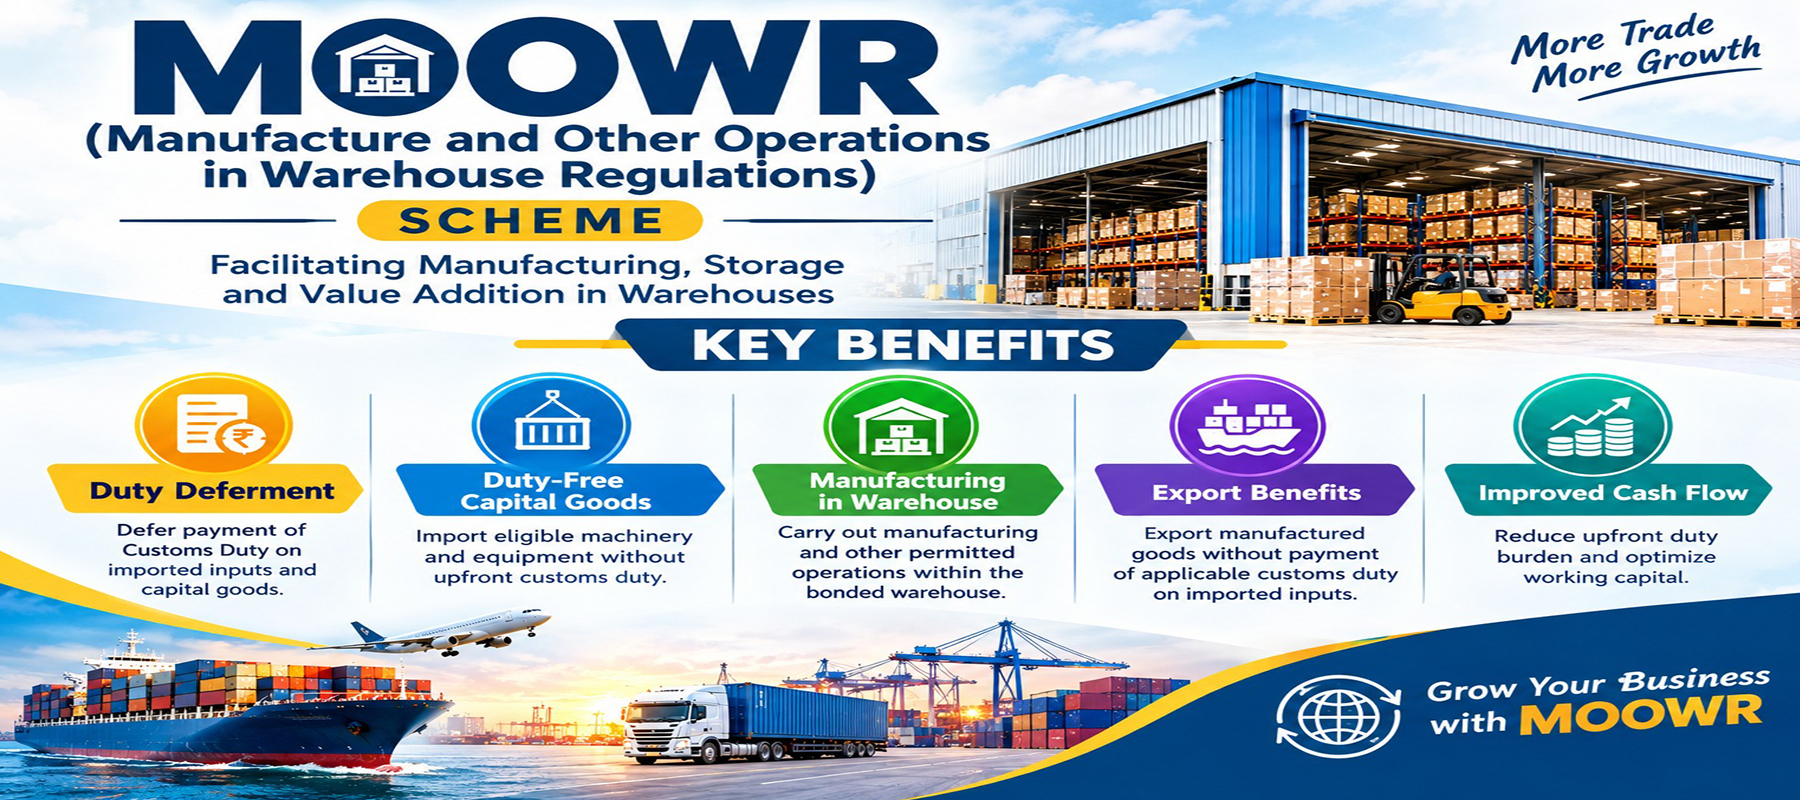
The MOOWR (Manufacturing and Other Operations in a Warehouse Regulations) Scheme,
introduced by the CBIC under Notification No. 69/2019-Customs (N.T.) dated October 1,
2019, is designed to promote and facilitate domestic manufacturing in India. Under the
scheme, eligible manufacturers can import inputs and capital goods without upfront
payment of applicable customs duties, with the duty liability being deferred while the
goods remain in the bonded warehouse.
The scheme helps businesses reduce working capital requirements, improve cash flow, and
enhance manufacturing competitiveness, while supporting the Government's “Make in India”
initiative and India's objective of becoming a global manufacturing hub.
What Is the MOOWR Scheme?
The Manufacture and Other Operations in Warehouse Regulations (MOOWR) Scheme is a
regulatory framework governed by Section 65 of the Customs Act, 1962. It enables
eligible importers and manufacturers to import inputs and capital goods without upfront
payment of applicable customs duties, provided the goods are warehoused and used for
manufacturing or other permitted operations within an approved bonded facility.
Under the MOOWR Scheme, the applicable customs duty liability is deferred and generally
becomes payable when the imported goods or resulting products are cleared for domestic
consumption. Goods exported from the bonded facility can benefit from the applicable
export treatment, subject to the prevailing customs provisions.
Key Characteristics of the MOOWR Scheme
1
Duty Deferment
Eligible imported inputs and capital goods can be warehoused without upfront payment
of applicable customs duties, including Basic Customs Duty (BCD) and IGST, subject
to the conditions of the scheme.
2
No Mandatory Export Obligation
Unlike schemes such as EPCG and Advance Authorisation, MOOWR does not impose a
prescribed export obligation. Businesses can manufacture for both domestic and
international markets.
3
Long-Term Authorisation
Once the facility is approved under the MOOWR framework, there is generally no
periodic renewal requirement, and the authorisation remains valid subject to
continued compliance and applicable customs provisions.
4
Digital Compliance & Record-Keeping
Businesses are required to maintain appropriate electronic records, inventory
details, and transaction documentation to ensure transparency and facilitate customs
compliance.
5
Improved Working Capital
By deferring customs duty payments until the applicable stage of clearance, MOOWR can
help businesses reduce working-capital requirements and improve cash flow.
Who Benefits Most from the MOOWR Scheme?
The MOOWR Scheme can be particularly beneficial for businesses with significant import
requirements, manufacturing operations, and a need to optimize working capital.
- Import-Intensive Industries: Industries such as electronics, automotive
components, pharmaceuticals, engineering, and other manufacturing sectors can
benefit from deferred customs duty on eligible imported inputs and capital goods.
- MSMEs & Growing Manufacturers: MOOWR can be attractive for MSMEs and
expanding businesses, as it does not prescribe a mandatory export obligation,
allowing them to manufacture for both domestic and international markets.
- Job-Work & Outsourced Manufacturing Models: Businesses using job-work or
outsourced processing arrangements can structure their operations within the
permitted MOOWR framework, subject to applicable customs requirements and controls.
- Domestic Market-Focused Manufacturers: Businesses primarily serving the
Indian market can benefit from duty deferment, with applicable customs duties
becoming payable at the relevant stage when goods are cleared for domestic
consumption.
- Businesses Seeking Working-Capital Efficiency: Companies with substantial
imported inputs or capital goods can use MOOWR to defer duty payments, improve cash
flow, and optimize working capital.
Our Expertise, Your Advantage
Kelular Consulting is a team of experienced professionals with in-depth knowledge of
MOOWR (Manufacturing and Other Operations in Warehouse) procedures, customs compliance,
and bonded warehouse regulations. We assist manufacturers and importers in understanding
the MOOWR framework, assessing eligibility, preparing documentation, and coordinating
the application process for obtaining MOOWR approval.
Our team provides end-to-end support to help businesses establish and operate under the
MOOWR scheme while ensuring compliance with applicable customs requirements. From
initial consultation and documentation to application submission and post-approval
guidance, we help simplify the process and minimize compliance challenges.
Why Choose Kelular Consulting?
- Expert MOOWR Knowledge - In-depth understanding of MOOWR procedures, customs
regulations, and compliance requirements.
- End-to-End Assistance - Support from eligibility assessment and documentation to
application and post-approval compliance.
- Documentation Support - Assistance in preparing and reviewing the required bonds,
declarations, insurance, and supporting documents.
- Customised Guidance - Solutions tailored to your business model, manufacturing
activities, and import requirements.
- Compliance-Focused Approach - Helping businesses maintain proper records and comply
with applicable customs and warehousing requirements.
- Process Monitoring - Regular follow-up and coordination to help ensure the
application progresses smoothly.
- Practical Industry Experience - Business-oriented guidance focused on making the
MOOWR framework easier to implement and manage.
How Kelular Consulting Can Help
Eligibility Assessment Documentation Application Preparation Customs Coordination MOOWR Approval Post-Approval Compliance Support
With Kelular Consulting, businesses can navigate the MOOWR process with greater clarity,
efficiency, and confidence while focusing on their core manufacturing and trading
operations.
MOOWR allows businesses to defer payment of customs duties on goods
imported into a licensed bonded warehouse under Section 65 of the
Customs Act. The duty remains deferred for as long as the imported goods
are stored in the warehouse or used in the manufacture of goods meant
for export.
Customs duty becomes payable only when the imported goods or the finished
products manufactured from them are cleared for domestic consumption.
This helps businesses improve cash flow and reduce the working-capital
burden associated with upfront duty payments.
The duty deferment can cover Basic Customs Duty (BCD), IGST, Social
Welfare Surcharge (SWS), Compensation Cess, Agriculture Infrastructure
and Development Cess (AIDC), and applicable trade remedial duties, such
as anti-dumping and safeguard duties, until ex-bond clearance.
No. MOOWR does not impose any mandatory export obligation, unlike the
EPCG and Advance Authorisation schemes. Businesses can use the MOOWR
facility for manufacturing and other permitted operations without being
required to achieve a specified export target.
Yes, MOOWR can be used alongside certain other customs and foreign trade
schemes, such as IGCR, Advance Authorisation, or EPCG, subject to the
specific conditions of each scheme. However, the same imported goods
cannot simultaneously claim overlapping duty benefits under multiple
schemes.
The permissibility of combining these schemes depends on the applicable
legal provisions, eligibility requirements, and conditions prescribed
under each scheme.
Under the MOOWR Regulations, 2019,
a unit is required to arrange the following:
-
Insurance Policy:
Coverage for the goods stored in the bonded
warehouse, as prescribed under the applicable
regulations.
-
Triple Duty Bond:
A bond covering the customs duties and other
applicable liabilities on the warehoused goods.
-
Indemnity Bond:
An undertaking to safeguard the Government
against any loss, liability, or non-compliance
arising in connection with the warehoused goods.
If the imported capital goods are subsequently
cleared for domestic sale, the
deferred customs duty becomes payable.
The duty liability is determined in accordance
with the applicable MOOWR provisions and is
generally based on the duty that was
deferred at the time of import, subject
to the applicable valuation and statutory
requirements.
No. MOOWR does not have a fixed
application deadline. Eligible
businesses can apply for the MOOWR facility
as required, subject to fulfilling the
prescribed conditions and requirements.
Once granted, the MOOWR licence remains
valid until it is cancelled or surrendered,
subject to continued compliance with the
applicable regulations and conditions.
Unlike SEZ and
EOU schemes,
MOOWR (Manufacturing and Other
Operations in Warehouse) does not
impose a mandatory export obligation, making
it a more flexible option for businesses that
have a significant domestic sales component.
Similarly, Advance Authorisation
and EPCG are subject to
specific export obligation and compliance
requirements. In contrast,
MOOWR primarily provides customs duty
deferment on eligible imported goods,
subject to the applicable conditions, without
imposing a mandatory export target.
|
|
|
|
|